Your CPA, Financial Advisor, and Estate Attorney Should Be Talking—Here’s Why
August 31, 2026
Tax, investment, and estate planning decisions often overlap. Learn why coordination among your CPA, financial advisor, and estate attorney can help create a more cohesive financial and legacy strategy.
For business owners, high-net-worth families, and individuals navigating a major financial transition, important decisions rarely fit neatly into a single category.
Selling a business can create tax consequences, change an investment strategy, and require updates to an estate plan. Gifting assets to family members may affect estate planning goals while also creating tax and investment considerations. Even decisions that appear relatively straightforward—such as how an account is titled or which assets are used to fund a trust—can have implications across several areas of a family’s financial life.
That is why your CPA, financial advisor, and estate attorney should not operate in separate silos.
Each professional brings a different perspective. The opportunity comes from making sure those perspectives are connected.
Three Professionals, Three Different Responsibilities
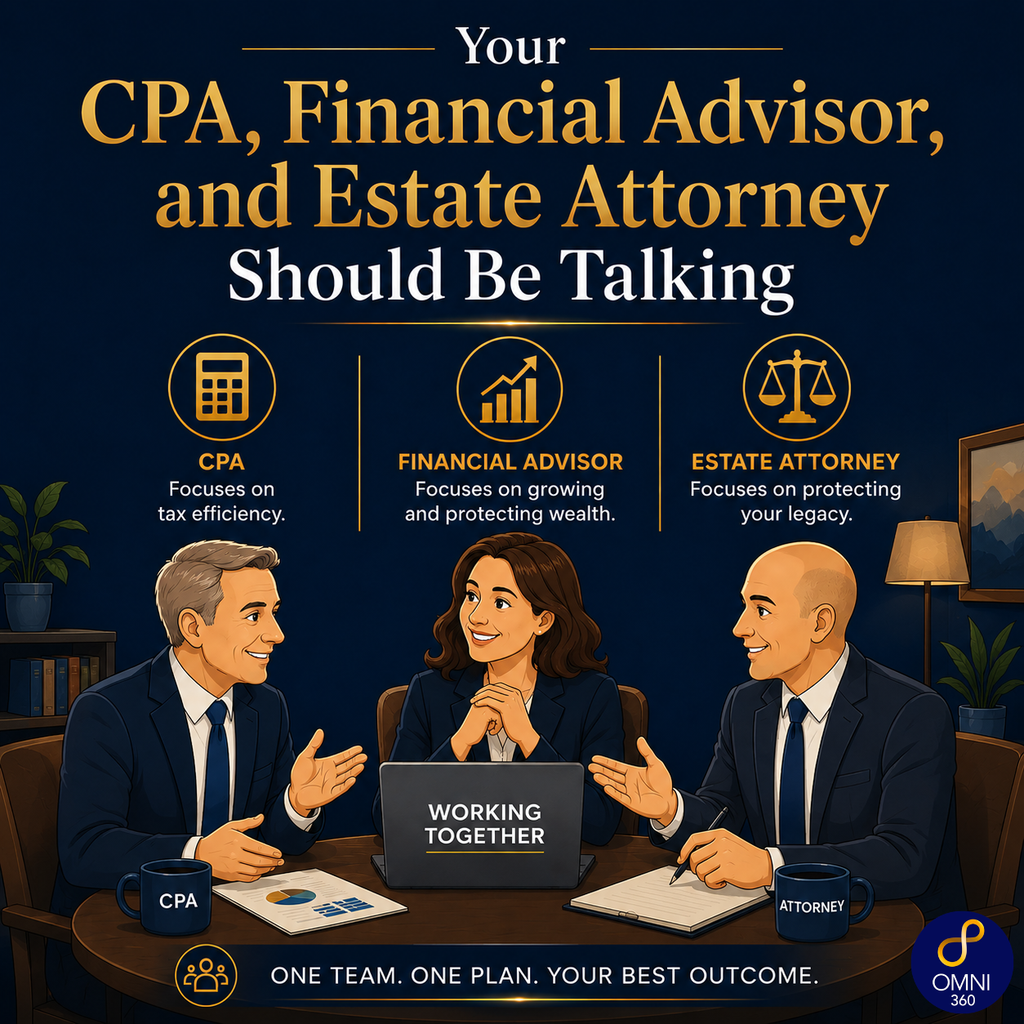
Your CPA generally focuses on tax reporting, tax planning, and the financial implications of transactions.
Your financial advisor considers your assets, cash flow needs, investment strategy, risk exposure, retirement objectives, and broader financial priorities.
Your estate attorney focuses on the legal structures designed to carry out your wishes, including wills, trusts, powers of attorney, asset ownership, and wealth-transfer planning.
All three roles are important. But the decisions they address frequently overlap.
A strategy that makes sense from a tax perspective may affect liquidity. An investment decision can influence an estate-planning objective. A trust drafted years ago may no longer align with how assets are currently owned.
When each professional sees only one piece of the picture, opportunities for better coordination can be missed.
Where a Lack of Coordination Can Create Problems
Consider a business owner preparing for a sale.
The CPA may be evaluating potential tax consequences. The financial advisor may be planning how sale proceeds could support future income, investment, and family goals. The estate attorney may be considering whether ownership interests should be transferred or estate documents updated before the transaction.
Timing matters.
If these conversations happen independently—or certain professionals are brought in only after a transaction is complete—the family may have fewer planning alternatives available.
The same principle applies outside of business sales.
A family may establish a trust but never coordinate the trust with account registrations or beneficiary designations. An individual may make a significant charitable gift without considering its effect on cash flow or other planning priorities. Someone may exercise stock options or sell a concentrated position without the tax professional and advisor discussing the broader implications beforehand.
None of these situations automatically means a decision is wrong. They illustrate why financial decisions are often interconnected.
Coordination Matters Most During Major Transitions
Certain life and financial events make collaboration especially valuable.
A business sale or other liquidity event can affect taxes, investments, cash flow, charitable planning, and wealth transfer at the same time. Retirement may require decisions involving account distributions, taxes, insurance, estate documents, and investment positioning. Changes in family circumstances—such as marriage, divorce, births, deaths, or changes in business ownership—can also create reasons to revisit an existing plan.
For multigenerational families, coordination becomes even more important as the number of people, entities, trusts, businesses, and accounts involved increases.
The objective is not simply to have more advisors. It is to create greater alignment among the professionals already helping you.
Your Financial Plan Should Function as One Plan
Clients sometimes think of tax planning, investment management, and estate planning as three separate exercises.
In practice, they are often parts of the same conversation.
For example, an estate-planning recommendation may determine which assets move to a trust. That decision can create investment-management considerations. Future sales or distributions from those assets can then have tax consequences.
Looking at these questions together can help identify conflicts, unanswered questions, and planning considerations before decisions are implemented.
That does not mean every professional needs to participate in every conversation. It means the team should know when a decision crosses into another professional’s area and communicate accordingly.
Questions to Ask Your Advisory Team
If you are unsure whether your professionals are communicating effectively, consider asking:
- Does my financial advisor have a current copy of my estate-planning documents?
- Does my CPA know about significant investment, gifting, or liquidity decisions being considered?
- Does my estate attorney understand how my major assets are owned and managed?
- Before a major transaction, have the relevant professionals discussed the decision together?
- Who is responsible for identifying when another member of the advisory team should be involved?
These questions can be particularly useful before a business sale, large gift, retirement, inheritance, major portfolio change, or significant update to an estate plan.
Better Planning Starts With Better Communication
Sophisticated financial lives tend to create interconnected decisions. Treating tax, investment, and estate planning as completely separate disciplines can make it harder to see the full picture.
At Omni 360 Advisors and Omni Legacy Law, we believe thoughtful planning includes understanding how financial, tax, business, and estate-planning decisions interact. For business owners and families facing important transitions, bringing the right professionals into the conversation at the right time can support a more coordinated decision-making process.
This blog was developed with the assistance of AI-based tools for research, drafting and editing support (ChatGPT), and reviewed by OMNI 360 personnel for accuracy and relevance. The information provided is educational and general in nature and is not intended to be, nor should it be construed as, specific investment, tax, or legal advice.