DIY Investing vs. Hiring a Wealth Manager: When Does Professional Financial Guidance Make Sense?
October 29, 2026
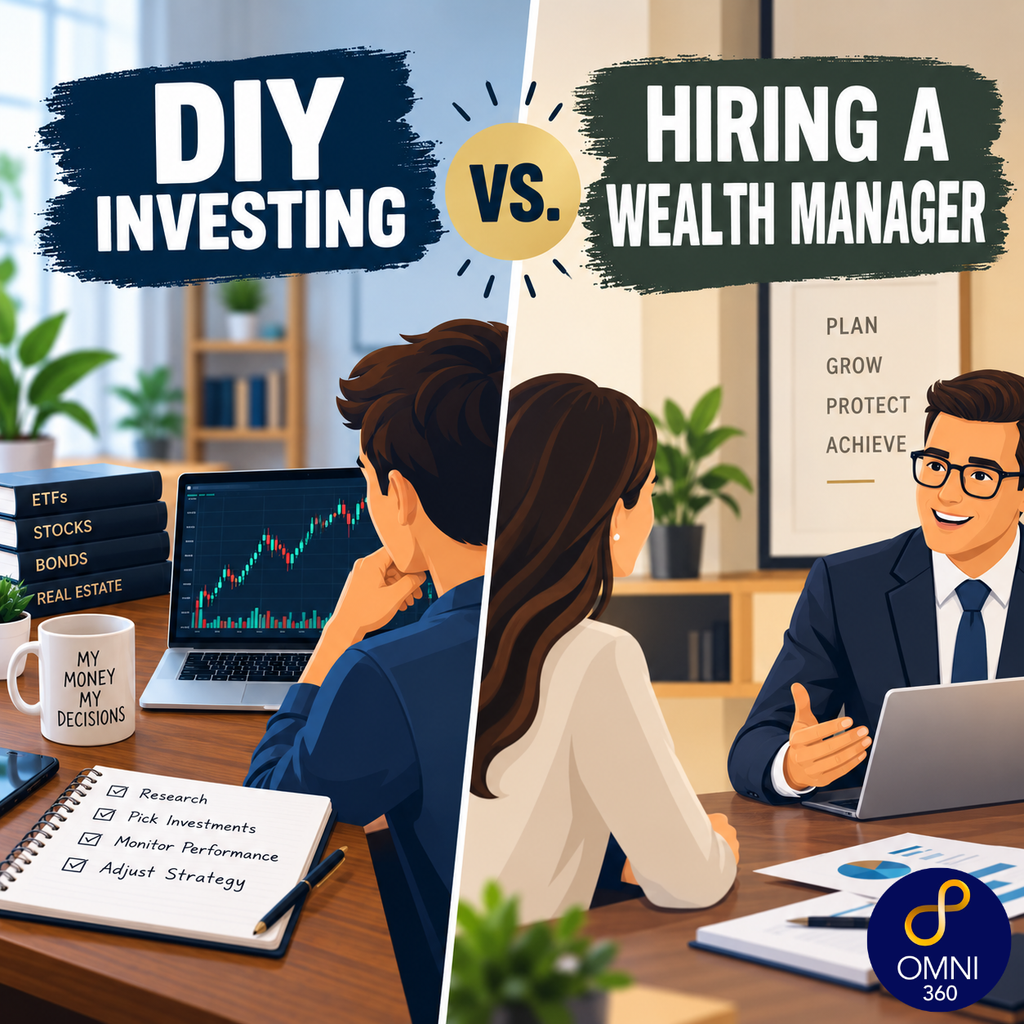
Should you manage your own investments or hire a wealth manager? Explore the benefits, costs, and considerations of professional financial guidance versus DIY investing.
Managing Your Own Wealth or Working With an Advisor: How Do You Decide?
With today’s investment platforms, financial apps, and access to information, managing your own investments has become more accessible than ever.
For some individuals, a do-it-yourself (DIY) approach can be practical and effective. For others, particularly business owners, executives, and families with increasingly complex financial lives, professional guidance may become more valuable as their circumstances evolve.
The question isn’t simply whether you can manage your investments yourself.
It’s whether managing your investments independently continues to make sense given your time, knowledge, financial complexity, and long-term objectives.
Understanding the differences between DIY investing and working with a wealth manager can help you make a more informed decision.
When DIY Investing May Make Sense
Managing investments independently can be appropriate for individuals with relatively straightforward financial circumstances, a solid understanding of investment fundamentals, and the time to monitor their portfolios.
A DIY approach may be worth considering if you:
- Have a relatively simple financial situation with limited planning needs.
- Understand asset allocation, diversification, and investment risk.
- Are comfortable making investment decisions during periods of market volatility.
- Have the time and interest to monitor your portfolio and financial progress.
- Prefer direct control over investment decisions and associated costs.
Low-cost index funds, diversified investment products, and digital investment platforms have made building and maintaining a portfolio more accessible.
However, investing independently also means taking responsibility for tax considerations, portfolio adjustments, risk management, and coordinating investment decisions with broader financial goals.
For some, those responsibilities are manageable. For others, they may become increasingly demanding.
When Working With a Wealth Manager May Be Worth Considering
As wealth grows, financial decisions often become more interconnected.
What begins as a relatively simple investment portfolio may eventually involve multiple retirement accounts, business interests, real estate, concentrated stock positions, charitable objectives, and estate planning considerations.
A wealth manager can help evaluate how these different elements interact.
1. Your Financial Life Has Become More Complex
Business ownership, executive compensation, inheritance, or a significant liquidity event can introduce new financial decisions.
These circumstances may require coordination across investments, retirement income, taxes, and estate planning.
Professional guidance may help organize these moving parts into a more cohesive financial strategy.
2. Tax Planning Has Become an Important Consideration
Investment decisions can have consequences beyond portfolio performance.
Asset location, tax-efficient withdrawals, capital gains, charitable giving, and retirement account distributions may influence a household’s overall tax picture.
A wealth manager can work alongside tax professionals to evaluate these considerations as part of a broader financial plan.
3. You’re Approaching Retirement or a Major Transition
Accumulating wealth and drawing income from investments present different challenges.
Retirement planning may involve determining sustainable withdrawal approaches, evaluating Social Security timing, managing liquidity, and accounting for inflation and market uncertainty.
These decisions often benefit from evaluating multiple scenarios rather than focusing solely on investment selection.
4. Your Time Is Better Spent Elsewhere
For business owners and professionals, time is a limited resource.
Managing investments involves more than selecting securities. It can require ongoing research, portfolio monitoring, reviewing tax implications, and revisiting financial assumptions.
Delegating certain responsibilities to an advisor may allow individuals to focus more attention on their businesses, careers, families, or personal priorities.
5. You Want an Objective Perspective
Financial decisions are not purely mathematical.
Market volatility, personal experiences, and emotional responses can influence investment behavior.
An advisor can provide an additional perspective, help evaluate alternatives, and encourage decisions grounded in established financial objectives rather than short-term market movements.
Professional guidance does not eliminate investment risk or prevent mistakes, but it can introduce a structured decision-making process.
Understanding the Cost of Professional Advice
Working with a wealth manager involves fees, and those costs deserve careful consideration.
Advisory fees may be based on assets under management, fixed arrangements, hourly services, or other compensation structures.
The services provided can also vary significantly.
Before engaging an advisor, it’s reasonable to understand:
- How the advisor is compensated and what services are included.
- Whether financial planning extends beyond investment management.
- How investment recommendations are developed.
- What potential conflicts of interest exist.
- How the advisor coordinates with accountants, attorneys, and other professionals.
The relevant comparison is not simply the cost of an advisor versus the cost of DIY investing. It is whether the services offered address needs that matter to your circumstances.
For individuals with straightforward portfolios, professional wealth management may add costs without providing enough additional value to justify them.
It Doesn’t Have to Be All or Nothing
One often-overlooked option is a hybrid approach.
An individual may choose to manage certain investment accounts independently while seeking professional guidance for retirement planning, tax coordination, business transitions, or estate-related decisions.
The appropriate level of assistance can also change over time.
A strategy that made sense early in a career may need to evolve as income, family responsibilities, assets, and financial objectives change.
Final Thoughts: The Right Approach Depends on Your Financial Life
DIY investing and professional wealth management are not competing philosophies. They are different approaches to managing financial responsibilities.
For some individuals, managing investments independently offers sufficient flexibility and control. For others, increasing financial complexity creates a need for broader coordination and ongoing guidance.
At Omni 360 Advisors, we believe effective wealth planning begins with understanding the complete financial picture, not simply an investment account.
Whether you’re navigating business ownership, preparing for retirement, evaluating a liquidity event, or considering your family’s long-term financial legacy, the goal is to make informed decisions that reflect your priorities.
If you’re evaluating whether professional wealth management makes sense for your circumstances, we welcome a conversation about your goals, questions, and available planning options.
This material is for general educational purposes only and should not be construed as individualized investment, tax, or legal advice. Investing involves risk, including potential loss of principal. The appropriateness of any financial strategy depends on individual circumstances.
This blog was developed with the assistance of AI-based tools for research, drafting and editing support (ChatGPT), and reviewed by OMNI 360 personnel for accuracy and relevance. The information provided is educational and general in nature and is not intended to be, nor should it be construed as, specific investment, tax, or legal advice.