Tax Facts: Retirement Benefits

December 17, 2014

When it comes to retirement accounts, it may feel like you have more questions than answers, even if you have had your retirement account for a long period of time. Assets that are held in qualified plans and IRAs have no current income tax liability, but the distribution of assets in those plans to participate or participant beneficiaries in future tax years can generate income tax liability at typical income tax rates. where-will-your-retirement-money-come-from
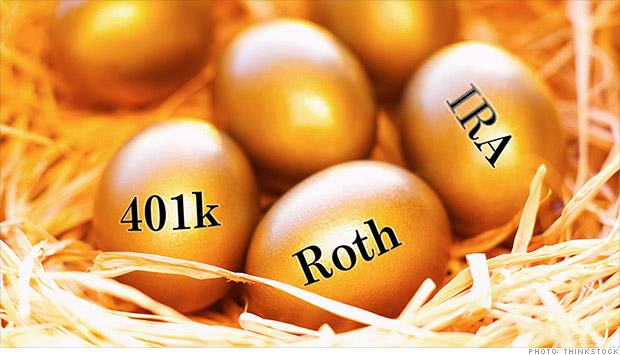
There are tax penalties if you attempt to request a distribution from an account before you have actually retired. The IRS actually imposes a tax penalty for funds that are withdrawn too soon and those that were not drawn out soon enough. For example, if you attempt to tap assets before reaching age 59 1/2, you’ll be responsible for paying both the ordinary income tax on the amount as well as a 10% tax penalty on those early distributions (although there are some limited exceptions to this. You may also be responsible for paying state income tax in some locations, too. You should always consult with your tax specialist before making a decision to tap into those assets.

As with all accounts, it’s important to know how you plan to use them in your own lifetime but also how future generations or a beneficiary is intended to use those accounts. Regardless of your age, it’s wise to add an account beneficiary. To talk about how to incorporate retirement accounts into your estate plan, give us a call at  732-521-9455.

Practice Areas:


Schedule your free Exploratory phone call

Click here to see how we
can be of assistance.

Payment Portal
for Tax and Accounting invoice

This link offers a secure, quick way to complete your payment with Omni360 Advisors LLC.

Our Social Media

Connect with us on Social Media using the following buttons:

Visit our Podcasts

Listen in, Join the Conversation!

Recent Posts

Your Tax Return Is a Roadmap: What to Review Before Year-End

Your completed tax return can reveal planning opportunities before year-end. Review investment gains, business income, retirement contributions, and estimated tax payments with your tax and ...

<p>The post Your Tax Return Is a Roadmap: What to Review Before Year-End first appeared on Integrated Tax Planning, Legal Planning & Financial Planning.</p>

Business Owners: Five Financial Conversations to Have Before December

Before year-end, business owners should review profit projections, cash reserves, major purchases, retirement plan funding, and personal financial goals with their advisory team. The start ...

<p>The post Business Owners: Five Financial Conversations to Have Before December first appeared on Integrated Tax Planning, Legal Planning & Financial Planning.</p>

Before You Make a Year-End Financial Move, Ask How It Affects the Rest of Your Financial Picture

Before making year-end tax, investment, retirement, business, or charitable decisions, consider how each move affects your broader financial picture. Year-end financial planning often starts with ...

<p>The post Before You Make a Year-End Financial Move, Ask How It Affects the Rest of Your Financial Picture first appeared on Integrated Tax Planning, Legal Planning & Financial Planning.</p>