The Family Financial Meeting: 10 Things Your Children Should Know Before They Need to Know Them
September 17, 2026
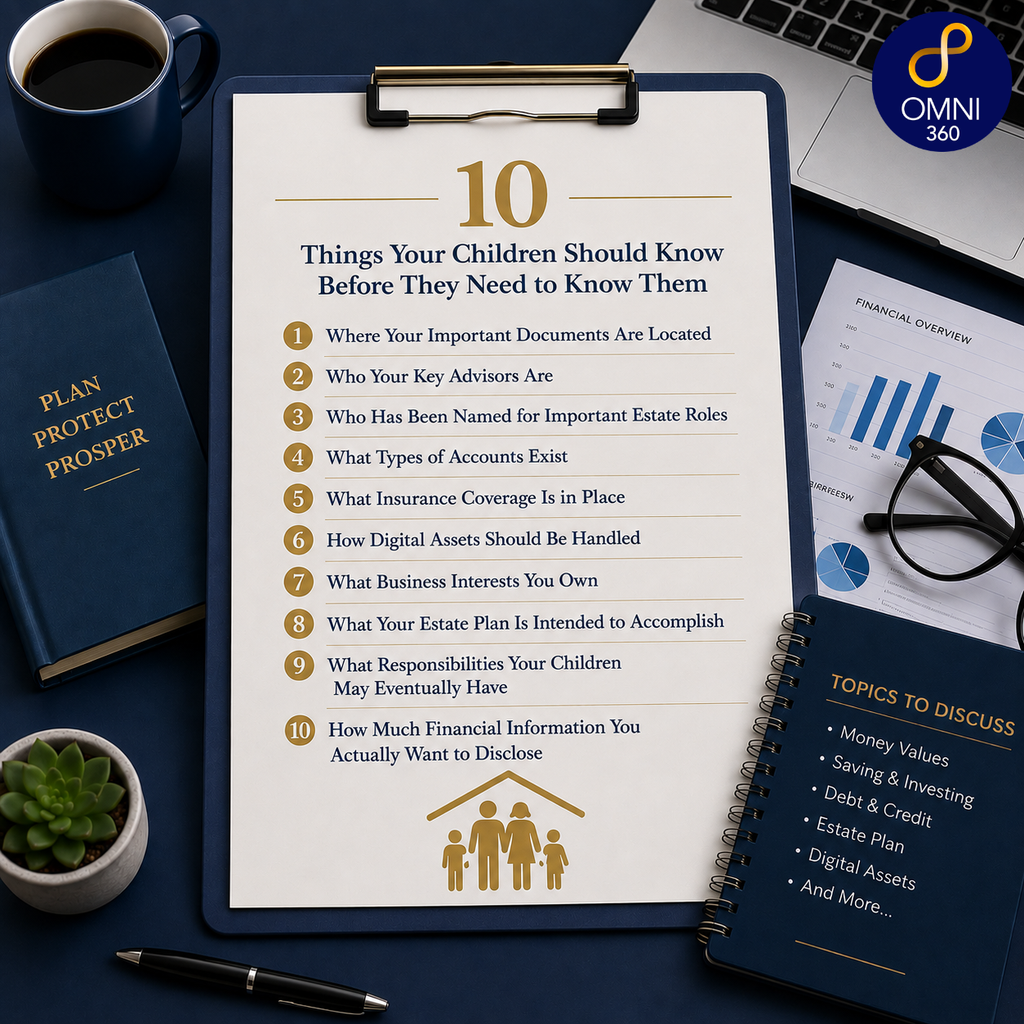
A family financial meeting can prepare adult children for future responsibilities without revealing every financial detail. Here are 10 things they should know before a crisis occurs.
For many families, conversations about money happen only when circumstances force them to happen.
A parent becomes ill. A spouse dies. A business owner can no longer manage day-to-day responsibilities. Suddenly, adult children are searching for documents, trying to identify advisors, figuring out account access, and making important decisions while the family is already under stress.
A family financial meeting can help prevent that scenario.
The goal is not necessarily to disclose your net worth, open every account statement, or involve your children in every financial decision. It is to make sure the people who may someday have responsibilities know enough to act thoughtfully when the time comes.
Here are 10 topics worth covering.
1. Where Your Important Documents Are Located
Your children do not necessarily need copies of everything, but someone should know where to find your estate planning documents, insurance policies, business records, property information, tax records, and other essential paperwork.
If documents are stored digitally, explain how the appropriate person can gain access when necessary.
2. Who Your Key Advisors Are
Provide the names and contact information for the professionals who understand your financial and legal affairs.
That may include your financial advisor, estate planning attorney, CPA, insurance professional, business attorney, or other trusted professionals.
Knowing whom to call can be almost as important as knowing where the documents are.
3. Who Has Been Named for Important Estate Roles
Adult children should understand who has been named as executor, trustee, financial power of attorney, and healthcare decision-maker.
These roles carry real responsibilities. Ideally, the people selected for them should learn about their appointments before they are called upon to serve.
4. What Types of Accounts Exist
You do not have to hand your children a detailed balance sheet.
However, it can be helpful for the appropriate family members to understand the broad financial landscape: bank accounts, investment accounts, retirement plans, real estate holdings, trusts, and other significant assets.
The objective is awareness, not necessarily full disclosure.
5. What Insurance Coverage Is in Place
Life insurance, long-term care coverage, disability insurance, property coverage, and other policies may become important during a family transition.
Children who may assist with financial matters should know which policies exist, where records are kept, and whom to contact.
6. How Digital Assets Should Be Handled
Increasingly, a family’s financial life includes digital property.
That may include online financial accounts, cloud storage, social media, cryptocurrency, digital photographs, subscription services, domain names, and other electronically stored assets.
Families should have a secure process for authorized access rather than simply sharing passwords casually.
7. What Business Interests You Own
For business-owning families, this conversation is especially important.
Children should understand at least the basics of what you own, whether there are partners or other shareholders, whether succession arrangements exist, and whom they should contact if you suddenly cannot manage the business.
They do not need to become experts overnight. They do need a roadmap.
8. What Your Estate Plan Is Intended to Accomplish
Estate planning documents explain what should happen. A family conversation can help explain why.
If assets are being left in trust, distributed unequally, directed toward charity, or structured differently for different family members, sharing your intentions can reduce uncertainty later.
You do not have to justify every decision. But context can help prevent assumptions and misunderstandings.
9. What Responsibilities Your Children May Eventually Have
Some children may inherit assets without having an administrative role. Others may serve as trustee, executor, business successor, or healthcare decision-maker.
Make those distinctions clear.
A child who will eventually carry significant responsibility may also benefit from meeting your advisors before an emergency occurs.
10. How Much Financial Information You Actually Want to Disclose
One of the biggest concerns parents have is: How much do I have to tell them?
Often, the answer is less than parents assume.
A productive family financial meeting does not require revealing exact account balances or a total net worth. You can share information in layers.
For example, your children might initially need to know that an estate plan exists, who is responsible for carrying it out, where documents are located, which professionals to contact, and the general types of assets involved.
More detailed information can be shared when appropriate based on age, maturity, family circumstances, and future responsibilities.
Preparation Without Overexposure
A good family financial meeting is not about surrendering privacy. It is about reducing avoidable confusion.
Families may choose to have one comprehensive conversation or several smaller discussions over time. Either approach can work. The important thing is that essential knowledge does not remain entirely with one person.
For business owners, multigenerational families, and individuals with more complex estates, coordinating the financial, legal, tax, insurance, and family pieces can be particularly valuable.
Omni 360 Advisors and Omni Legacy Law help families think through these conversations as part of broader financial and legacy planning. A well-prepared family does not need to know every detail today—but the right people should know enough to respond when tomorrow arrives.
This blog was developed with the assistance of AI-based tools for research, drafting and editing support (ChatGPT), and reviewed by OMNI 360 personnel for accuracy and relevance. The information provided is educational and general in nature and is not intended to be, nor should it be construed as, specific investment, tax, or legal advice.