When Your Financial Life Becomes Too Complicated for a Collection of Separate Advisors
September 14, 2026
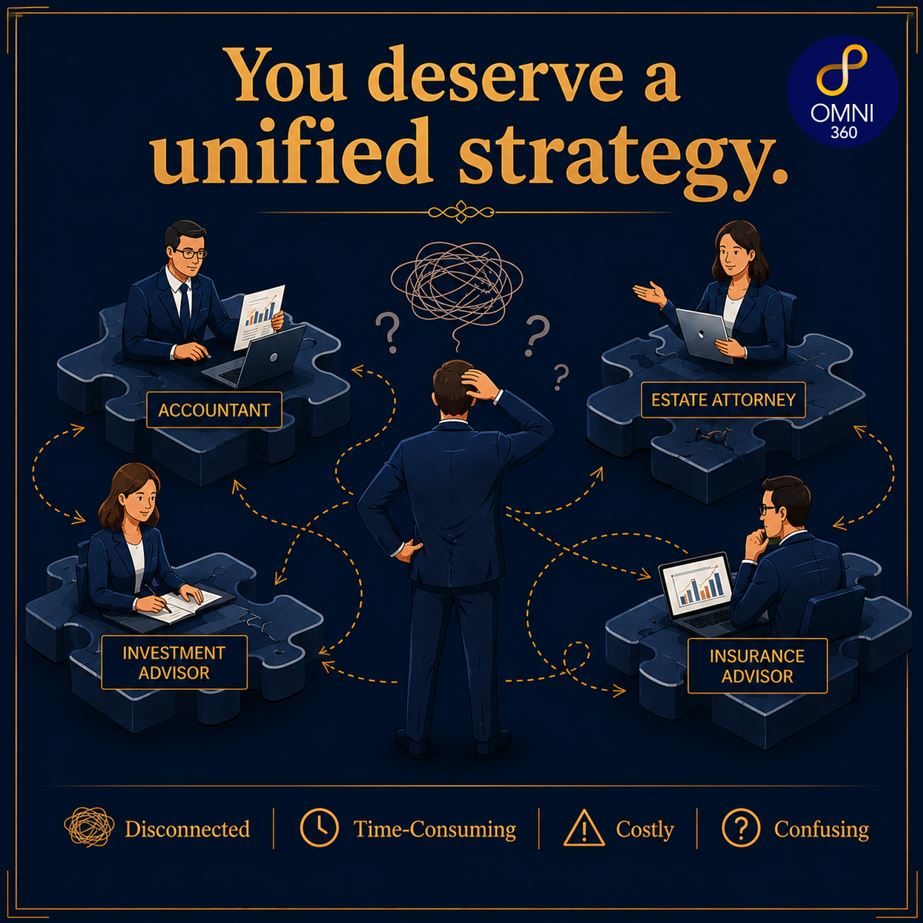
As wealth grows more complex, separate advisors can create gaps between business ownership, real estate, trusts, investments, taxes, retirement plans, and family goals. Learn why coordinated planning matters.
For many successful business owners and families, financial complexity does not arrive all at once. It builds gradually.
A business grows. A second property is purchased. An investment account is opened somewhere else. Trusts are established. New tax entities are created. Retirement plans become more sophisticated. Children enter the business—or choose a different path. Eventually, what began as a relatively straightforward financial life becomes a network of interconnected decisions.
At that point, having several capable professionals may no longer be enough.
The challenge is not necessarily the quality of each advisor. It is whether everyone is working from the same picture.
Complexity Changes the Nature of Financial Planning
A business owner may have a CPA focused on tax filings, an attorney responsible for estate documents, an investment advisor overseeing a portfolio, an insurance professional reviewing coverage, and additional specialists connected to real estate or retirement plans.
Each professional may be doing excellent work within his or her area.
But your financial life does not operate in separate departments.
A decision involving the business may affect personal cash flow. A real estate transaction may influence tax planning. The ownership structure of an asset may affect an estate plan. A trust may need to coordinate with beneficiary designations. A retirement plan decision may interact with business succession and long-term family objectives.
The more interconnected the financial picture becomes, the more important coordination becomes.
Business Ownership Adds Another Financial System
For business owners, personal wealth and business wealth are often deeply connected.
The company may represent a significant portion of the owner’s net worth, provide current income, fund retirement savings, employ family members, own property, or eventually become part of a succession or liquidity strategy.
That creates questions that cannot always be addressed effectively in isolation.
How does the business fit into the owner’s estate plan? What happens if ownership transfers to the next generation? How should personal liquidity be considered alongside concentrated business value? Are retirement plans aligned with the company’s broader financial strategy?
These are not simply business questions or personal financial questions. They sit at the intersection of both.
Multiple Properties and Entities Create Additional Layers
Real estate can add another level of complexity, particularly when properties are owned through LLCs, partnerships, trusts, or other entities.
A family may own a primary residence, vacation property, commercial real estate, and investment properties—each with different financing, tax, insurance, cash-flow, and estate-planning considerations.
Meanwhile, various entities may have their own tax filings, ownership structures, operating agreements, and long-term purposes.
Looking at each property or entity independently can make it harder to understand the family’s total exposure, liquidity needs, and overall balance sheet.
Coordinated planning creates a more complete view.
Trusts and Estate Planning Must Connect to the Rest of the Picture
Estate planning is another area where disconnected decisions can create unintended gaps.
A trust may be thoughtfully drafted, but it still needs to align with the assets that are actually owned, the way those assets are titled, and the beneficiary designations attached to retirement accounts, insurance policies, and other financial accounts.
For families with multiple generations, the questions can extend well beyond document preparation.
Who should eventually own or control the family business? How should responsibility be transferred? What role should children or grandchildren have in managing family wealth? Are there different expectations for family members who work in the business and those who do not?
Effective legacy planning requires financial, legal, tax, and family considerations to work together.
Investments Are Only One Part of the Financial Picture
An investment portfolio may be important, but for financially complex families, it is rarely the entire plan.
Investment decisions should be viewed alongside business concentration, real estate holdings, liquidity requirements, tax obligations, retirement assets, trusts, charitable intentions, and future transfers of wealth.
Without that broader context, individual decisions can make sense on their own while working against another part of the family’s strategy.
The objective of coordinated planning is not to eliminate specialized advisors. In many cases, specialists remain essential.
The goal is to make sure specialized advice connects to a shared strategy.
The Shift From Having Advisors to Having a Coordinated Advisory Team
There is a meaningful difference between having several advisors and having an advisory team.
A collection of advisors may each receive different information, work from different assumptions, and focus on separate deadlines. A coordinated team works from a broader understanding of the family’s priorities and recognizes when one decision affects another.
For business owners, post-liquidity families, and multigenerational households, that coordination can become increasingly important as wealth expands across businesses, properties, investment accounts, trusts, retirement plans, and tax entities.
Complexity itself is not necessarily a problem. Fragmentation can be.
Omni 360 Advisors and Omni Legacy Law work with individuals, business owners, and families who want to view their financial, business, and legacy decisions as parts of one interconnected picture. If your financial life has reached the point where decisions regularly cross professional disciplines, a conversation about greater coordination may be a useful place to begin.
This blog was developed with the assistance of AI-based tools for research, drafting and editing support (ChatGPT), and reviewed by OMNI 360 personnel for accuracy and relevance. The information provided is educational and general in nature and is not intended to be, nor should it be construed as, specific investment, tax, or legal advice.